Key Takeaways
- FEMA's map sets your zone: Search your exact address at the FEMA Flood Map Service Center. Distance from Hinkson Creek or Flat Branch does not decide it.
- Work in the floodplain needs a City permit: Columbia requires a Floodplain Development Permit for any land disturbing activity in the regulatory floodplain (City of Columbia).
- The 50 percent rule shapes a buyer's plans: Work costing half the structure's market value triggers a lowest floor two feet above base flood elevation (Columbia Code 29-1.11, 29-2.3(d)(9)(i)).
- Citywide risk is a small share: Redfin's First Street panel lists 1,173 sites, about 3% of Columbia, at severe flood risk over 30 years (Redfin, September 2026).
- Put water history on paper: No Missouri statute creates a general seller disclosure form, yet a written note of past water entry protects you and informs the buyer.
- An as-is sale stays open to you: Columbia's floodplain rules attach to permitted work, so nothing has to be raised or repaired first. A direct cash buyer can fold the creek questions into a single price.
If you want to sell a house in a flood zone in Columbia, Missouri, start with one calm step. Look up your address on FEMA's flood map, then learn the few City rules a buyer will ask about. A house near a creek is not automatically in a mapped flood zone, and FEMA's map is what decides it.
This guide covers where Hinkson Creek and Flat Branch run and what the Hinkson Creek gauge records. It also explains how to read your zone, the City's Floodplain Development Permit, the 50 percent rule, flood insurance, and flood disclosure in Missouri. The last section compares three ways to sell a Columbia house with flood questions.
Why wait? Sell your house “as is” for cash today
Tell us about your house. We'll make you a cash offer based on local market data.
Let's chatWhere Do Hinkson Creek and Flat Branch Run in Columbia?
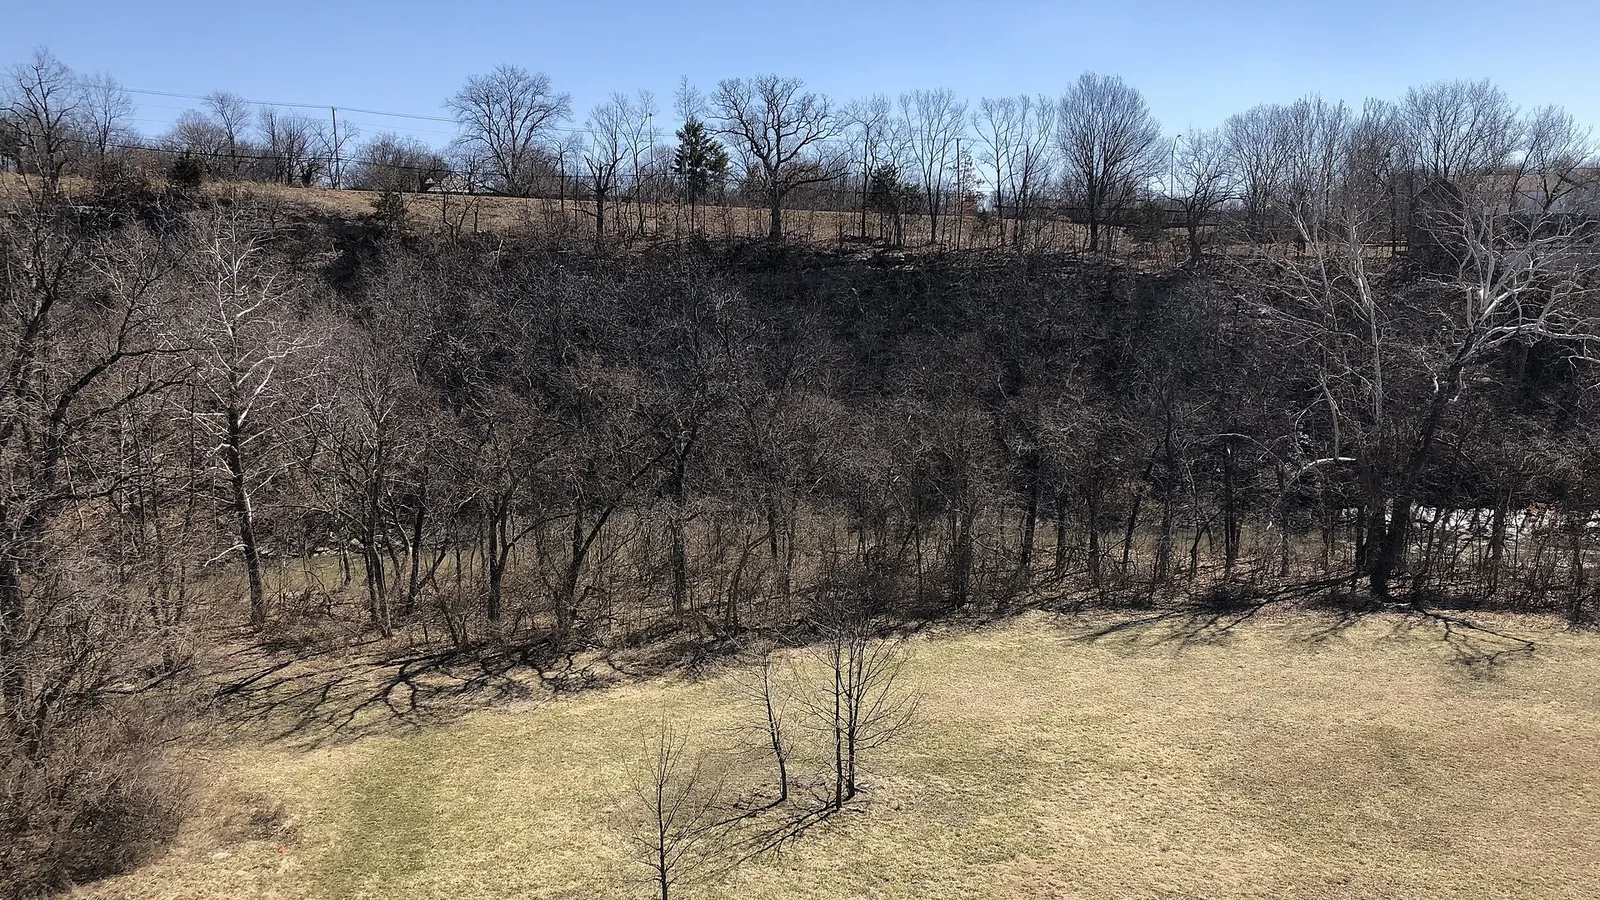
Hinkson Creek runs southwest through Columbia, Missouri, and Flat Branch drains the interior of the city before it joins the Hinkson. The City's watershed page calls the Hinkson Creek watershed the largest in Columbia (City of Columbia, Watersheds, read October 2026).
Hinkson Creek
Hinkson Creek is 26 miles long and drains roughly 88.5 square miles, all in Boone County. It starts east of Hallsville, a separate town north of Columbia. It then flows southwest through the city and joins Perche Creek in southwest Columbia (City of Columbia, Watersheds).
Several large tributaries feed the Hinkson inside the Columbia area. That is why houses along side branches can share the same flood questions as houses on the main creek.
Flat Branch
The City lists Flat Branch as a tributary of Hinkson Creek. Flat Branch and County House Branch drain the interior of Columbia, including older central neighborhoods (City of Columbia, Watersheds). A house can sit near a small branch and still fall outside any mapped flood zone.
Creek names describe where water drains. FEMA's Flood Insurance Rate Map is what lenders, insurers, and the City use to decide whether a parcel sits in a regulated floodplain. Check the map before you assume anything.
What the Hinkson Creek Gauge Records
The National Weather Service tracks Hinkson Creek through gauge TGRM7, "Hinkson Creek at Columbia," near the Providence Road bridge. It sets action stage at 13 feet, minor flooding at 15, moderate at 18, and major at 20 (National Weather Service, gauge TGRM7, read October 2026). The gauge pairs with USGS station 06910230.
The Weather Service notes that forecasts for this gauge "are issued as needed during times of high water." Routine forecasts are not posted. The page does show current readings for anyone who wants to follow the creek.
Past readings at the gauge
The highest crest the Weather Service lists is 23.45 feet on June 25, 2021. Other high readings include 22.4 feet on April 30, 2009, and 20.67 feet on September 14, 2008. Two 2026 readings, 20.8 feet on June 8 and 19.45 feet on August 6, are marked preliminary (NWS TGRM7, read October 2026). They describe what the creek has done, not what it will do.
The gauge's impact notes describe stream banks, a soccer field, a parking lot, and Providence Road near the bridge. At 20.9 feet, for example, water reaches the height of Providence Road just north of the gauge bridge. A reading at one bridge says little about a particular house elsewhere on the creek.
How Do You Check Your Flood Zone in Columbia, MO?
To check your flood zone in Columbia, MO, enter the street address on the FEMA Flood Map Service Center and note the zone the effective Flood Insurance Rate Map assigns to that parcel. The City states that FEMA establishes the floodplain boundaries and publishes the maps (City of Columbia, Building and Site Development, read October 2026).
Reading the result
- A, AE, and the other A-series labels mark the Special Flood Hazard Area. FEMA calls this "the area where the mandatory purchase of flood insurance applies" (FEMA glossary, read October 2026).
- An AE label comes with a base flood elevation, the number Columbia's two-foot rule builds on. FEMA defines it as the water level from a flood with a 1% chance of reaching or passing that height in any given year (FEMA glossary).
- X zones fall outside the high-risk area on the map. Heavy rain on the Hinkson watershed can still put water in a yard or basement there.
Download the panel and keep it with your closing papers. The FIRM panel number is also the item the City's permit form asks for, so the same page serves a buyer, a lender, an insurer, and a future permit. One printout answers the first question each of them will ask.
The 3% figure and your parcel
Redfin's climate panel, using First Street data, lists 1,173 sites in Columbia at severe flood risk over the next 30 years. That is about 3% of the city (Redfin, September 2026). The figure is a model for the whole city. A buyer weighing a house on Hinkson Creek or Flat Branch looks past that share to three things: the parcel's zone, how high the lowest floor sits, and any past claims.
The Columbia Floodplain Development Permit
The Columbia floodplain development permit is required for any land disturbing activity within the regulatory floodplain, according to the City. The City participates in the National Flood Insurance Program, which requires a local ordinance and enforcement of floodplain development rules (City of Columbia, Building and Site Development, read October 2026).
What the application asks
The City's Flood Plain Development Permit Application covers development in the Special Flood Hazard Area. It asks for several facts about the site:
- Whether the site is in a designated floodway or in the floodplain fringe.
- The elevation of the 1% base flood and of the proposed development site.
- The FIRM panel number for the parcel.
- Other permits, such as a Corps of Engineers 404 permit.
In a floodway, the form requires certification that the work will cause no increase in base flood elevations before a permit is issued. The City also links FEMA's Elevation Certificate form from its permit page. Questions go to Building and Site Development at 573.874.7474.
Why a seller should know this
You do not need this permit to sell. A buyer who plans to add on, regrade, or rebuild inside the floodplain will need it. That buyer will ask what the lot's base flood elevation is and how high the lowest floor sits. An elevation certificate answers both questions in one document.
The 50 Percent Rule and the Two-Foot Elevation Standard
Columbia's 50 percent rule says work that costs at least half the structure's market value is a substantial improvement, and the house must then meet the floodplain elevation standard. Both rules sit in chapter 29, the Unified Development Code (Columbia Code of Ordinances, Municode).
The text of Columbia's two rules
Section 29-1.11 defines a substantial improvement for floodplain purposes as work whose cost "equals or exceeds fifty (50) percent of the market value of the structure." Section 29-2.3(d)(9)(i) then sets the standard for houses:
“New construction or substantial improvements of any residential building ... shall have the lowest floor, including basement, elevated to at least two (2) feet above base flood elevation.” (Columbia Code 29-2.3(d)(9)(i))
FEMA uses the same 50 percent threshold for substantial damage, meaning damage from any cause that would cost half the pre-damage market value to repair. A community's building official or floodplain administrator makes that call, not FEMA or an insurer (FEMA, Substantial Damage FAQ, read October 2026).
How the two-foot rule reaches a sale
Consider a made-up example for illustration only. If the structure is valued at $200,000, a $100,000 renovation reaches the 50 percent line. In the floodplain, that could turn a kitchen and basement remodel into a project to raise the lowest floor or fill the basement.
The federal NFIP minimum asks only for a lowest floor "elevated to or above the base flood level" (44 CFR 60.3(c)(2)). Columbia adds two feet on top of that, a margin a renovating buyer has to plan for. None of this blocks a sale. It changes what a renovating buyer can afford to pay. If the house needs more than flood-related work, see what an as-is sale looks like in our guide to selling a house that needs major repairs.
What applies where
| Where the house sits or what happens | What the rule requires | Source |
|---|---|---|
| Any zone, at sale | No repair or elevation required to sell. Known meth production must be disclosed in writing; pre-1978 houses need a lead paint disclosure. | RSMo 442.606; EPA |
| Zone X (outside the SFHA) | No federal flood insurance purchase requirement. Coverage is optional. | FEMA glossary |
| Zone A or AE (SFHA), financed purchase | Flood insurance required with a mortgage from a government-backed lender. | FEMA, Flood Insurance |
| Regulatory floodplain, any land disturbing work | Floodplain Development Permit from the City. | City of Columbia, Building and Site Development |
| Designated floodway | Certification of no increase in base flood elevations before a permit issues. | City permit application |
| Work costing 50% or more of the structure's market value | Counts as a substantial improvement. | Columbia Code 29-1.11 |
| New or substantially improved house in the floodplain | Lowest floor, including basement, at least two feet above base flood elevation. | Columbia Code 29-2.3(d)(9)(i) |
The elevation standard is triggered by building and repair work. A deed changing hands is not a permit, so a sale on its own triggers nothing. Raising the floor before you list is your choice, never a City requirement.
Flood Insurance for a Columbia Buyer
Flood coverage is bought as its own policy, and FEMA requires it when a buyer finances a house in a high-risk flood area through a government-backed lender. In FEMA's words, "most homeowners insurance does not cover flood damage" (FEMA, Flood Insurance, read October 2026).
Columbia and the NFIP
The federal flood program is run by FEMA under the name National Flood Insurance Program, or NFIP. The City of Columbia takes part in the program, and that participation is the reason the City enforces its floodplain permit. FEMA says a fresh NFIP policy usually waits 30 days before coverage starts, with exceptions such as coverage a lender requires.
Where insurance shows up in a Columbia sale
- The buyer's budget: A premium on an A or AE zone house raises the monthly cost of owning it, and a lender counts that cost when sizing the loan.
- The closing calendar: The 30-day wait means a financed buyer often shops for a quote early, sometimes before the inspection is done.
- Your paperwork: An elevation certificate lets an insurer rate the house on its real floor height instead of guessing.
Buying with cash removes the lender, and with it the federal purchase requirement. The insurance math does not vanish, though. A cash buyer who plans to keep or resell the house still prices in the premium the next owner will face.
Flood Disclosure in Missouri: What to Tell a Buyer
Missouri sellers should give a buyer known flood history and water damage in writing, even though no state statute prescribes a general disclosure form for houses. A buyer near Hinkson Creek will ask about water first, and a dated written answer carries more weight than a verbal one.
Two disclosures the law does spell out
- Meth production: A Missouri seller who knows methamphetamine was made on the premises must say so in writing (RSMo 442.606).
- Lead-based paint: For a house built before 1978, federal law adds a lead paint disclosure (EPA, read October 2026).
A short flood file for a Columbia house
- Each time water reached the living space, basement, or crawl space, and the approximate date.
- Any flood claim, the amount paid, and the work it covered.
- Repairs after water damage, plus City permits or contractor invoices.
- The FIRM panel and zone, and an elevation certificate if one exists.
A complete file can head off an argument after closing about what the seller knew. If the City has also sent a notice about the house, our guide to selling a Columbia house with an open code notice explains that separate rule. Treat this section as general information rather than legal advice, and ask a Missouri real estate attorney about your own facts.
Ways to Sell a House in a Flood Zone in Columbia, MO
Columbia sellers with a floodplain house generally choose between an agent listing, a sale to a renovating buyer, and an as-is sale to a direct cash buyer. The right one depends on the zone, the water history, and how soon you need to move. For context, Redfin reports a median sale price of about $293,360 in Columbia for the three months ending September 2026, with a typical sale taking about 36 days (Redfin, September 2026).
Zillow's ZHVI puts the typical Columbia value at about $321,671, up about 2.5% year over year (Zillow ZHVI, September 2026). Our Columbia, MO housing market 2026 report breaks those numbers down further.
Listing with an agent
A house in an X zone with a dry basement and good condition is the strongest candidate for a listing. In an A or AE zone, a financed buyer's lender will require flood coverage, so the quote becomes part of the deal. Bring the FIRM panel, any elevation certificate, and your flood file to the first meeting with an agent.
Selling to a renovating buyer
A buyer who plans a big remodel will price Columbia's two-foot standard into the deal. If the work would pass half the structure's value, the plan may need a Floodplain Development Permit and a raised floor. That expense comes off what the buyer can offer.
Selling as-is to a direct cash buyer
An as-is cash sale lets the creek questions travel with the house instead of landing on your to-do list. Propcash reviews the zone, the water history, and recent Columbia sales before making an offer. Propcash is a direct cash homebuyer that signs the purchase contract as the buyer, and you leave the repairs, cleaning, and showings behind.
You get one data-backed figure with the reasoning laid out. There are no fees or commissions to Propcash, and the closing date is yours to choose. A closing can happen in as few as 7 days after the contract is signed. When a listing looks like the better fit for your house, we tell you that plainly. To weigh our number against a listing, get a cash offer or start with our Columbia, MO cash buyer page, which walks through the local steps.
Our roundup of the best ways to sell a house for cash in Columbia, MO lays every option side by side.
Why wait? Sell your house “as is” for cash today
Tell us about your house. We'll make you a cash offer based on local market data.
Let's chatFrequently Asked Questions
How do you find out if a Columbia, MO house is in a flood zone?
Type the full street address into FEMA's Flood Map Service Center and note the zone shown on the effective Flood Insurance Rate Map panel for that parcel. An A or AE label marks FEMA's high-risk Special Flood Hazard Area, while X marks lower mapped risk. Living near Hinkson Creek or Flat Branch does not settle the question, because FEMA draws zones lot by lot.
Can you sell a house in a flood zone in Columbia, Missouri as-is?
You can sell a Columbia, Missouri house in a flood zone as-is, because no City rule requires you to repair or elevate it before a sale. The City's floodplain rules apply when someone builds, grades, repairs, or improves inside the floodplain. A buyer who plans major work takes on those rules, so the zone and any water history tend to shape the price.
When do you need a Columbia floodplain development permit?
The City of Columbia says any land disturbing activity within the regulatory floodplain requires a Floodplain Development Permit. The application asks for the base flood elevation, the FIRM panel number, and whether the site is in a floodway. Questions go to the City's Building and Site Development office.
What is the 50 percent rule in Columbia's floodplain code?
Columbia's code treats work as a substantial improvement when its cost equals or exceeds 50 percent of the market value of the structure (Columbia Code 29-1.11). A new or substantially improved residential building in the floodplain must have its lowest floor, including the basement, at least two feet above base flood elevation (29-2.3(d)(9)(i)). In practice, a remodel that crosses the line can become a project to raise the floor or fill the basement.
Does a Columbia seller have to disclose past flooding?
A Columbia seller should tell a buyer about known flooding in writing, although Missouri has no statute that prescribes a general disclosure form. The written rules Missouri does have cover known meth production (RSMo 442.606), and federal law requires a lead paint disclosure for pre-1978 houses. A Missouri real estate attorney can advise on your own facts.
Does a buyer need flood insurance for a house in a Columbia flood zone?
A buyer with a mortgage from a government-backed lender must carry flood insurance on a house in a high-risk flood area, according to FEMA. Flood damage generally falls outside a standard homeowners policy, so the buyer needs a separate flood policy, such as one written through the NFIP, in which Columbia participates. FEMA says a new NFIP policy usually starts after a 30-day wait, with some exceptions.