Yes. A flooded West Palm Beach house can sell as-is, but Florida requires a written flood disclosure at or before the contract.
The form asks about flood damage during your ownership, flood claims, and flood assistance, and its definition includes standing rainwater. Inside the City's Special Flood Hazard Area, repairs costing 50 percent or more of the building's pre-damage value mean meeting current flood standards.
This is general information, not legal advice. State rules vary.
Jump to a section
Has your house taken water from flooding?
Free. No obligation. You choose the closing date.
If you want to sell a flooded house in West Palm Beach, you can, and no statute read for this guide requires repairs first. What Florida does require is a written flood disclosure, given to the buyer at or before the time the contract is signed (Fla. Stat. § 689.302). This guide walks through that form, the City's 50% rule, the flood records a buyer can pull on your address, and what happens to a flood policy at closing.
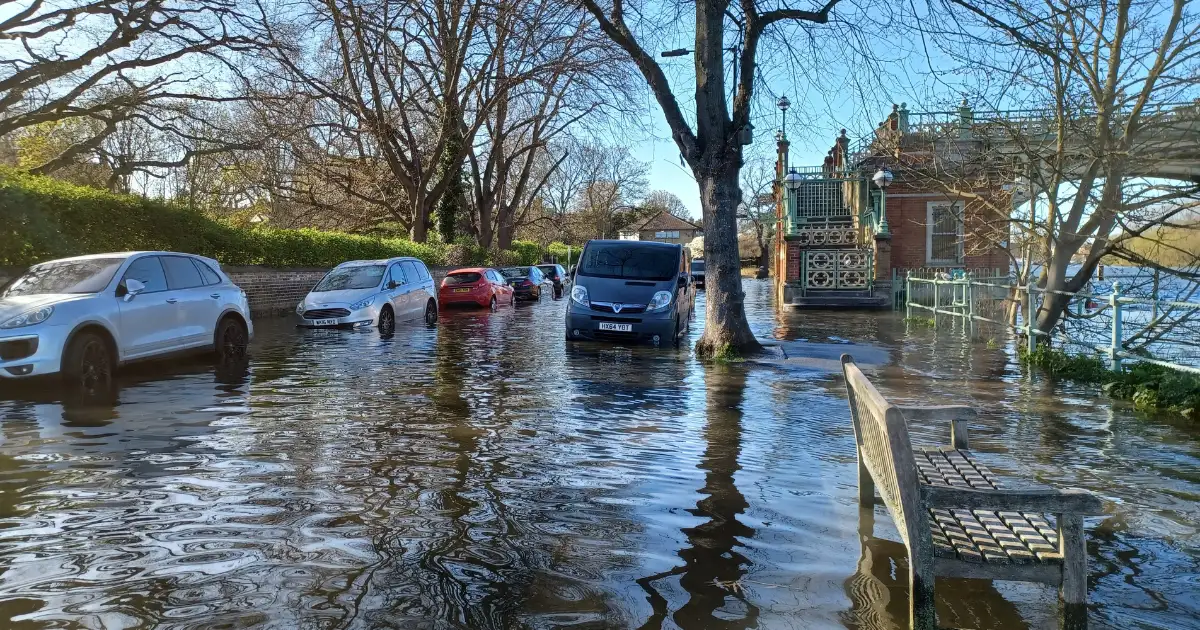
This month adds a layer. As of November 14, 2026, the City's Flood Information page carried a flooding update. It said Mayor Keith James had extended the City's local state of emergency through Sunday, November 15, 2026, “in response to ongoing flooding conditions and the potential for additional rainfall.” If water reached your house in recent weeks, nothing in this guide calls for a decision this week.
Can you sell a West Palm Beach house that just flooded?
Yes, a West Palm Beach house can be sold while it still shows flood damage, as long as the buyer receives Florida's flood disclosure at or before the contract. The disclosure statute asks what happened to the house. It does not ask what you fixed.
Damage changes who will buy and at what price, not whether a sale is allowed. A buyer with a mortgage may need the house to pass a lender's review. A cash buyer can take it in the condition it is in, wet drywall and all, and price the work into the offer.
What as-is can mean after water gets in
- You can leave damaged flooring, drywall, and cabinets where they are.
- You do not open repair permits for work you are not going to do.
- The buyer's price reflects the condition, and the contract says as-is.
- You still answer the flood disclosure questions in full.
Emergency declarations change as conditions change. The City posts the current status on its Flood Information page, so check there rather than relying on the date above.
Does the City's flood program cover your address?
The City of West Palm Beach floodplain rules, its flood insurance rating, and its flood map apply only inside the city limits. A house with a West Palm Beach mailing address outside those limits follows Palm Beach County rules instead.
The mailing address is not a reliable guide. Parts of ZIPs 33406, 33409, 33411, 33413, and 33415 use West Palm Beach as the city name but lie in unincorporated county land. The faster check is the parcel control number, read against the Property Appraiser's municipality list: its first two digits are 74 for West Palm Beach and 00 for unincorporated parcels.
Two things do not change at the city line. The Florida flood disclosure applies to residential sales everywhere in the state. Countywide offices, such as the Property Appraiser, serve houses on both sides.
What must a West Palm Beach seller disclose about flooding?
A Florida seller must give the buyer a written flood disclosure that answers three questions: known flood damage during your ownership, any flood insurance claim, and any flood assistance. It goes to the buyer at or before the time the sales contract is executed.
"A seller must complete and provide a flood disclosure to a purchaser of residential real property at or before the time the sales contract is executed."
Fla. Stat. § 689.302, Florida Statutes
The law is recent. It was created by chapter 2024-215, effective October 1, 2024. Chapter 2025-166 rewrote the form effective October 1, 2025, adding the question about damage you know of during your ownership.
| Item on the form | What the statute asks | What it reaches |
|---|---|---|
| (1) Known flood damage | Whether the seller has knowledge of flooding that damaged the house during the seller's ownership | Your years of ownership only, including water from this month if it caused damage |
| (2) Flood claims | Whether the seller has filed a claim with an insurance provider for flood damage | Any flood claim, including, but not limited to, the National Flood Insurance Program |
| (3) Flood assistance | Whether the seller has received assistance for flood damage | Any assistance, including, but not limited to, the Federal Emergency Management Agency |
| (4) What counts as flooding | Partial or complete inundation from listed causes | Overflow of inland or tidal waters; rapid runoff or surface water from an established source such as a drainage ditch; sustained standing water from rainfall |
Why rain-only flooding still matters
Many owners think of flooding as water from a lake or the ocean. The statute is wider. Its definition includes “Sustained periods of standing water resulting from rainfall,” which fits the kind of flooding the City's emergency extension describes.
The form also opens with a printed note telling the buyer that standard insurance policies do not cover flood damage. It encourages the buyer to talk with an insurance agent about separate flood coverage. A Florida real estate attorney can help with how to answer a borderline item.
How does the 50% rule affect a flooded house in the city?
Inside West Palm Beach's Special Flood Hazard Area, a building is substantially damaged when repairs cost 50 percent or more of its pre-damage market value. To get permits, it must then be brought up to code under current flood map standards, according to the City's Flood Information page.
The City spells out the math. Its test compares the cost of the repairs with the market value of the building before the damage occurred or repairs started. At 50 percent or more, the building counts as substantially damaged.
The permit steps the City lists
- Floodplain Development Permit first: it is required before building permits are issued for a project in the Special Flood Hazard Area.
- Elevation Certificate: required for all permitted work in that area, and used for flood insurance rating.
- Possible certifications: No-Rise or No-Impact certifications may also be required.
- Local ordinance: the City's Floodplain Management Ordinance sets the rules for development there, including work exempt from the Florida Building Code.
For an owner who wants to sell, the rule matters in two ways. If you repair first, your permit application may trigger the review. If you sell as-is, the buyer carries that review instead. Development Services answers permit questions at 561.805.6705.
A house in one of the City's historic districts adds another approval for exterior work. The guide to selling a historic house in West Palm Beach covers that review.
What flood records can a buyer check on your address?
A buyer can look up a West Palm Beach address on the City's interactive flood map and see its flood zone, elevation figures, and any Elevation Certificate on file.
According to the City, the City's flood map shows, for each address:
- Flood information, including whether the parcel is in an Otherwise Protected Area
- Base Flood Elevation and Design Flood Elevation
- Links to the FEMA Flood Insurance Rate Map
- Parcel information, plus a Files tab where an Elevation Certificate on file can be downloaded
The City also answers questions by phone at 561-805-6705. Its page lists what staff can tell a caller, including whether a house is in an area that has flooded repeatedly. The City also points to the county's Flood Zone Determination System, where anyone can type in an address to find its flood zone (county flood lookup).
Two figures a buyer may see
The City holds a Community Rating System Class 5, which the City says equates to a 25% discount on all National Flood Insurance Program policies issued in the City (City of West Palm Beach, read November 2026). That discount applies inside the city limits.
Buyers browsing listings may also see a risk panel. First Street data shown on Redfin says “2,518 properties in West Palm Beach are likely to be severely affected by flooding over the next 30 years,” which it puts at 23% (First Street via Redfin, read September 2026). That is a model estimate, not a record of any one house.
What happens to your flood policy when you sell?
An NFIP flood policy can move to the buyer: FEMA says a seller can transfer the policy to the new owner, regardless of whether there is a mortgage involved. Any flood claim you filed still belongs on the disclosure.
Timing is the other half. FEMA's real estate brochure says a 30-day waiting period typically applies to a new policy. There is no waiting period when the first purchase is tied to making, increasing, extending, or renewing a mortgage loan. The City's page makes the same point: in most cases, there is a 30-day waiting period before coverage takes effect.
The City also notes that NFIP flood insurance is available to everyone in West Palm Beach, including houses that have flooded and those outside a flood zone. What a policy costs a buyer is between that buyer and an agent. This guide does not predict rates. Broader insurance pressure on Florida sellers is covered in the Florida insurance crisis selling guide.
Repair, list, or sell the flooded house as-is?
Repairing first may raise the price but puts permits, contractors, and the 50% review on you, while selling as-is hands that work to the buyer. Listing as-is sits in between. Which fits depends on your money, your time, and how much you want to manage.
Time on the market is part of the math. Redfin data shows the typical West Palm Beach listing took 90 days to sell in the three months ending September 2026, down from 104 a year earlier. The median sale price was up 3.1% over the same stretch (Redfin, September 2026). Those are citywide figures for all sales, not for flooded houses.
| Path | Who handles repairs and permits | Flood disclosure | What can slow it down |
|---|---|---|---|
| Repair, then list | You, including any 50% review in the Special Flood Hazard Area | Required | Contractor schedules, permits, then time on the market |
| List as-is with an agent | The buyer, after closing | Required | Showings, inspections, and a buyer's lender review of the condition |
| Sell as-is to a cash buyer | The buyer, after closing | Required | Title work; no lender or listing period |
Open City matters travel with the house too. The City's lien search reports cover utilities, code violations, and receivables, and title companies typically request them during a sale. If flood cleanup led to a code case, the West Palm Beach code lien guide explains what a buyer's title work may find.
How can Propcash help with a flooded West Palm Beach house?
Propcash is a direct cash homebuyer, and we buy West Palm Beach houses as-is, flood damage included, with no repairs, cleaning, or permits on your side. You pick the closing date, and a cash sale can close in as few as 7 days after the contract is signed.
Our offers are based on local market data, and we'll show you how we got to our number. You still complete the Florida flood disclosure for us, the same as for any buyer. If repairing and listing looks like the better move, we will tell you, and you can walk away with no obligation. You can request a cash offer from Propcash and set it next to your other options, or start with our West Palm Beach cash house buyer page.
Frequently Asked Questions
Does standing rainwater count as flooding on the Florida disclosure?
It can. Fla. Stat. 689.302 defines flooding to include sustained periods of standing water resulting from rainfall, along with overflow of inland or tidal waters and rapid runoff from an established water source. If rain left water standing in a West Palm Beach house long enough to damage it during your ownership, the first question on the form is likely to apply. A Florida real estate attorney can help with a borderline case.
Do I have to fix flood damage before I sell in West Palm Beach?
No statute read for this guide requires repairs before a sale; Fla. Stat. 689.302 asks about flood history, not about repairs. A flooded house can be sold in its current condition when the contract says as-is. The buyer then decides whether to repair, and any repair inside the Special Flood Hazard Area goes through the City's permit and 50% review.
Can a buyer take over my NFIP flood policy?
Yes. FEMA's guidance for real estate professionals says a seller can transfer the policy to the new owner, regardless of whether there is a mortgage involved. A brand new policy typically starts after a 30-day waiting period, with an exception when it is bought in connection with a mortgage loan. Any claim you filed stays with you and still goes on the disclosure.
Who decides whether a flooded West Palm Beach house is substantially damaged?
Inside the city limits, the question comes up when someone applies for repair permits through the City's Development Services Department. The City's Flood Information page says a building is substantially damaged when the cost of repairs equals or exceeds 50 percent of its market value before the damage. The department takes questions at 561.805.6705.
What if my house has a West Palm Beach address but sits outside the city?
Then Palm Beach County rules apply, not the City's floodplain program, rating, or flood map. Parts of ZIPs 33406, 33409, 33411, 33413, and 33415 carry a West Palm Beach mailing address but lie in unincorporated county land. The Property Appraiser's parcel control number tells you: city parcels start with 74 and unincorporated parcels with 00. The Florida flood disclosure applies on both sides of the line.
Does selling to a cash buyer change what I have to disclose?
No. Fla. Stat. 689.302 applies to a seller of residential real property, and it does not carve out cash sales or as-is contracts. A cash buyer still receives the flood disclosure at or before the contract is signed. What a cash sale can change is the work: the buyer takes on the repairs, the permits, and the 50% review.
Data Sources: Florida Statutes 689.302 and Laws of Florida chapters 2024-215 and 2025-166. City of West Palm Beach Flood Information and City Lien Search pages; FEMA National Flood Insurance Program; Palm Beach County Property Appraiser; Redfin; First Street via Redfin. Propcash is a direct cash homebuyer, not a law firm. Sellers should consult a Florida-licensed attorney for case-specific guidance.
Reviewed by the Propcash Editorial Team under our editorial standards. Published by Propcash, a direct cash buyer of houses. This guide is general information. Laws, fees, and market figures change, so check the current rules for your state.