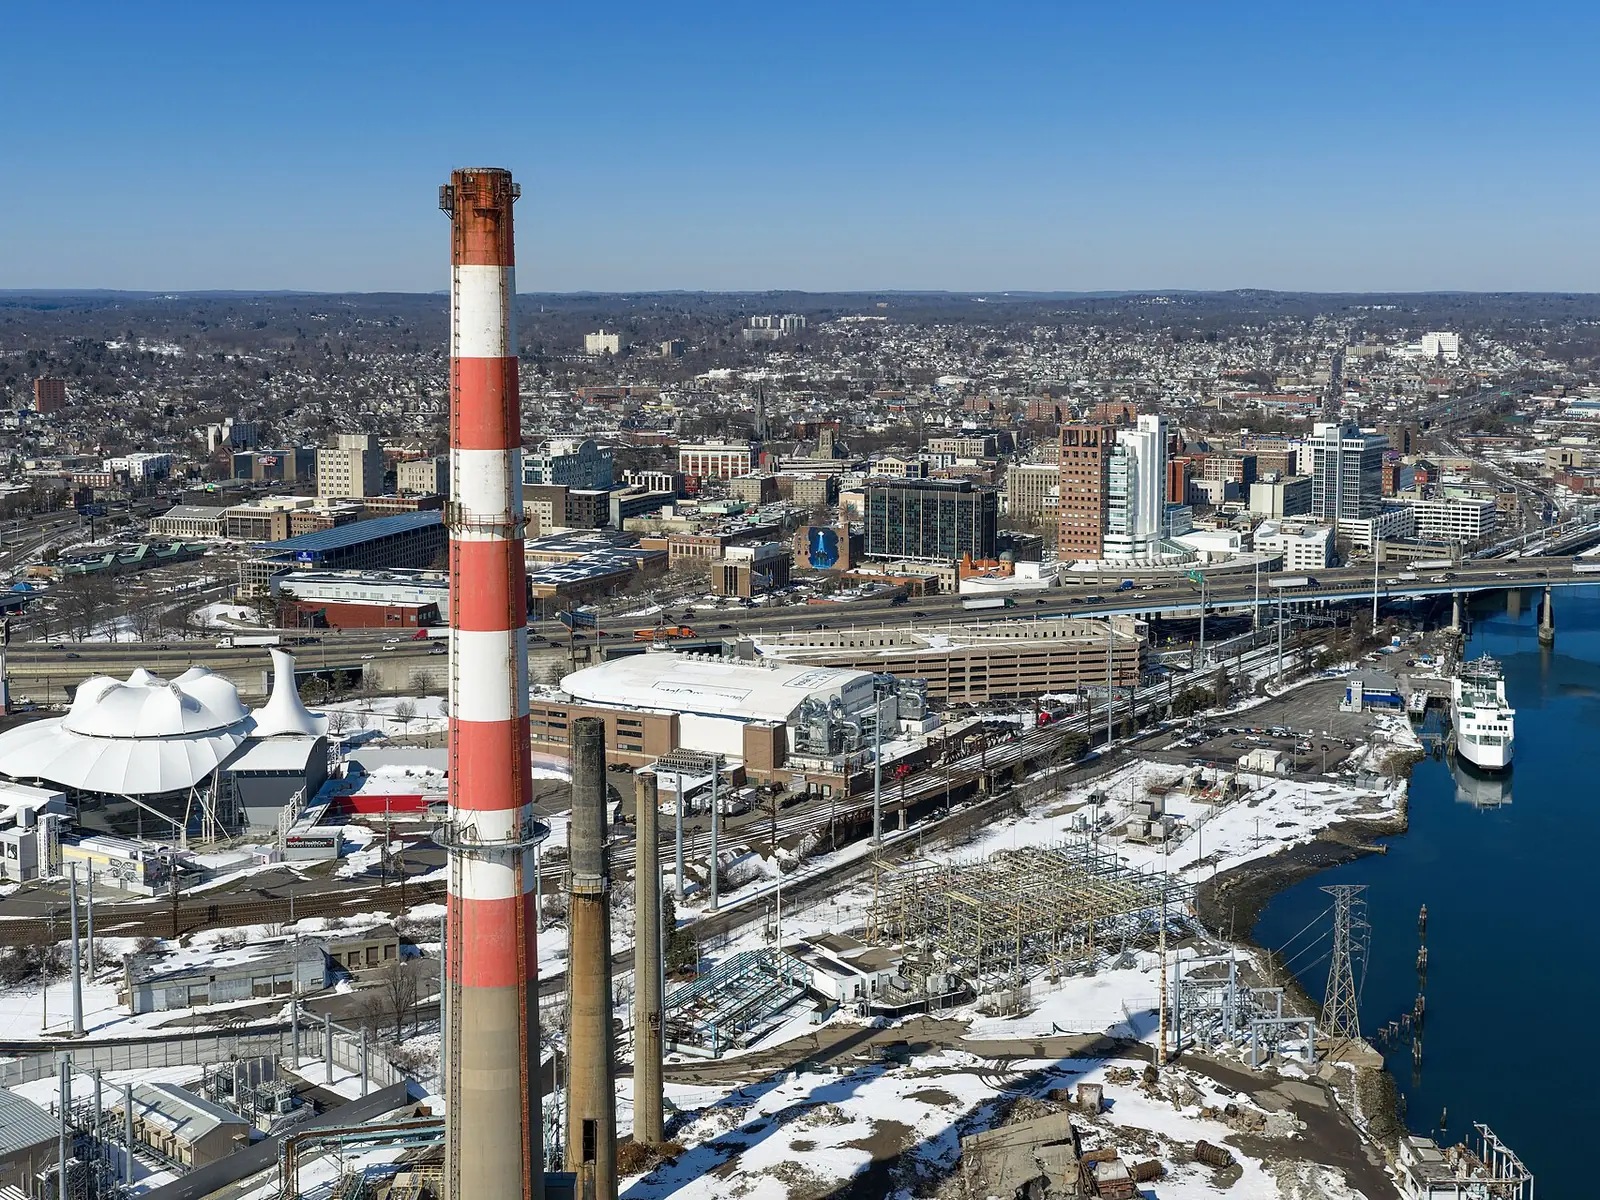
Sell Your House Fast in Bridgeport, CT, for a Fair Cash Offer
Propcash is a direct cash homebuyer making one fair, data-backed offer on houses like yours, as-is.
How do I sell my house fast in Bridgeport?
Selling your house fast in Bridgeport comes down to three moves: tell us about the property, get a cash offer priced against Fairfield County market data, and pick the day you close. The person who quotes your number is the same person you deal with the whole way through, and the house does not need to change before we buy it.
Tell us about your Bridgeport property
Give us the address, the condition, and your timeline, and that is it. Two minutes, and nothing is owed.
Get your cash offer
We compare your house against recent Fairfield County sales and put one cash number in writing, with no obligation attached.
Review your offer & close
Accept it or walk away, no hard feelings either way. Closing runs through a Connecticut attorney and title company in as few as 7 days.
Propcash's direct-buyer approach gets Bridgeport sellers a fair cash offer
A fair, data-based offer puts you in control.
- We buy your house directly
- A fair offer based on local market data
- Work directly with your point of contact
- Full transparency
- No obligation, walk away anytime
- We show you how we got to our number
Our offer stands
No 24-hour expirations, no countdown clocks. If the market shifts, we re-run the numbers rather than pressure you, and we follow up on your schedule.
We tell you if we're not the right buyer
If listing with an agent would clearly serve you better and you have the time, we will say so and point you to someone local.
How Propcash stacks up against other ways to sell a Bridgeport house
 That's us
If you have time and the house shows well, listing with an agent may net you more. If you want it done without repairs or showings, that is where we come in. We tell you straight either way.
Why do Bridgeport homeowners sell their houses for cash?
Tenant-occupied multi-families, estates stuck in probate, city violations, and flood-zone insurance trouble are the most common reasons Fairfield County owners call Propcash.
Relocating on a fixed date
Many Bridgeport owners commute to Stamford, Norwalk, or Manhattan on the Metro-North Line, and a job move comes with a start date, not a selling season. We can close ahead of it, no lender approval needed. Relocation guide.
Code violations mounting
Open permits and blight citations on an older Bridgeport house carry fines that compound while the repair bill grows. We buy houses with open code violations and sort them out ourselves after closing.
Inherited property
Inherited a Bridgeport two-family full of belongings? We help heirs sell inherited houses once the estate is opened and a fiduciary is named. Keep what you want and walk away from the rest. Inheritance guide.
An empty house you are still carrying
Taxes, insurance, and utilities keep arriving on a Bridgeport house nobody lives in, and an empty building degrades fast in a coastal climate. We buy vacant houses as-is, no cleanout required, and we also work with owners downsizing out of a house that got too big.
Divorce settlement
Connecticut splits marital property on what is equitable, not an even fifty-fifty line, so one transparent cash number turns the house into proceeds both spouses divide cleanly. See how we buy houses during a divorce. Divorce guide.
Tired of being a landlord
Done funding turnovers, boiler calls, and late rent on an East Side three-family? No need to empty the building first: leases carry over as they are. Here is how we work with tired landlords. Landlord guide.
What is the Bridgeport housing market doing in 2026?
Bridgeport prices are climbing while houses take longer to sell than a year ago, and the table below carries the numbers behind every offer we make. Redfin reports what has actually closed, and Zillow estimates the typical Bridgeport house citywide, so we never blend the two. A mill equals one dollar of tax per thousand dollars of assessed value, and your own assessment, not the headline rate, sets the bill (Connecticut OPM, 2026). A cash sale also fixes the closing date, as our cash offer versus traditional sale comparison lays out.
| Bridgeport market metric | Latest figure | Source |
|---|---|---|
| Median sale price (last 3 months) | About $412,227, up 5.7% year over year | Redfin, August 2026 |
| Typical time to sell | About 46 days, up from 43 a year ago | Redfin, August 2026 |
| Houses sold in the latest reported month | 246 in the three months ending August 2026, down from 250 a year earlier | Redfin, August 2026 |
| Typical house value (ZHVI) | About $364,989, up about 4.5% year over year | Zillow ZHVI, August 2026 |
| City real-property mill rate | 43.45 mills for fiscal 2026, on the 2024 Grand List | Connecticut OPM, FY 2026 |
| State conveyance tax, paid by the seller | 0.75% up to $800,000, then 1.25% and 2.25% by price band | Connecticut DRS, 2026 |
We buy houses in every Bridgeport neighborhood
From the waterfront blocks of Black Rock to the two- and three-family grid of the East Side, Propcash buys houses across Bridgeport and Fairfield County, in any condition.
House in Fairfield, Stratford, Trumbull, or Milford? We buy there too. Selling somewhere else in Connecticut? Up the shoreline on I-95 we help owners sell a house fast in New Haven, and north on Route 8 and I-84 you can sell a house for cash in Hartford.
Neighborhoods we buy in: sell your house fast in Black Rock, the South End, the East Side, the East End, and Downtown Bridgeport.
Bridgeport neighborhoods, from Black Rock to the East End
Every Bridgeport neighborhood sells differently, and the spread between the Black Rock waterfront and the blocks east of the harbor decides what a fair offer looks like.
Black Rock, Brooklawn, and the North End
Black Rock is Bridgeport's southwestern corner, on Black Rock Harbor and Ash Creek against the Fairfield town line, with the Black Rock Historic District listed on the National Register in 1979 and Black Rock Gardens added in 1990. The Fairfield Avenue strip and the St. Mary's-by-the-Sea shoreline walk anchor it, and the housing is old, substantial, and expensive to restore properly. Brooklawn and the North End hold quieter early- and mid-century single-family blocks where long-tenure owners weigh renovation against a sale.
The South End, Seaside Park, and the waterfront
The South End is a low-lying peninsula below downtown, home to the University of Bridgeport and to Seaside Park, the Sound-front park designed by Frederick Law Olmsted on land P. T. Barnum secured for the city in 1865. Tropical Storm Irene in 2011 and Superstorm Sandy in 2012 both pushed water into these blocks, and FEMA flood-zone designations along the waterfront drive insurance cost and lender caution. The city's post-Sandy resilience work is only partly built, so a coastal house here can still stall a financed buyer at underwriting.
The East Side and the Pequonnock corridor
The East Side is Bridgeport's dense industrial-era core east of the Pequonnock River, and its East Bridgeport Historic District, listed in 1979, covers the planned grid P. T. Barnum and William H. Noble laid out around Washington Park. This is two- and three-family country: wood-frame buildings owned by small landlords, often with tenants in place, aging boilers, and deferred maintenance a lender's appraiser flags. Selling one to a financed owner-occupant usually means emptying it first.
The East End and Mill Hill
The East End sits on the Sound east of the harbor and is Bridgeport's most affordable segment, with older working-class stock, higher vacancy, and the tax-lien pressure that turns a slow problem into a deadline. Mill Hill and the Boston Avenue corridor carry similar houses. Thin equity is the recurring theme, and it is why timing matters more here than the asking price.
Downtown, Golden Hill, and the West Side
Downtown is the arts and entertainment core, where old commercial buildings have been converted into lofts and condos across the Golden Hill, Downtown North, and Downtown South historic districts. Association assessments, non-warrantable condo rules, and historic-masonry lending friction thin the pool of buyers who can close on these units.
We buy across Fairfield County and throughout Connecticut. Ready now? Get a cash offer on your Bridgeport house.
Sell your Bridgeport house in any condition
You can sell your Bridgeport house exactly as it stands: no repairs, no cleaning, no cleanout.
Sagging porches on a century-old three-family, a buried oil tank, and an inherited code violation are precisely what a financed buyer's inspection flags.
- Multi-family structural issues
Foundation problems, sagging porches, and rotting sills in century-old two- and three-family buildings.
- Outdated electrical systems
Knob and tube wiring, undersized panels, and aluminum branch circuits that insurers will not cover.
- Building code violations
Open permits, blight citations, and city violations from a previous owner. None of it stops us from buying.
- Flood-zone and insurance friction
South End and waterfront houses where flood insurance cost and underwriting push financed buyers away.
- Oil tank issues
Underground tanks, abandoned tanks, and contamination questions, all handled after closing.
Illustrative repair costs Bridgeport sellers avoid by selling as-is to Propcash
Free guides for Bridgeport homeowners
The Connecticut disclosure, tax sale, strict foreclosure, probate, and foundation rules that apply to Bridgeport sellers, from Black Rock to the East End.
Behind on Property Taxes in Connecticut? Tax Sales Explained
Read the guide
Connecticut Seller Disclosure Requirements
Read the guide
How to Stop Foreclosure in Connecticut
Read the guide
Selling a House With a Crumbling Foundation in Connecticut
Read the guide
Selling an Inherited House in Connecticut
Read the guideWhat Bridgeport sellers are up against
A rising market does not help an owner whose building still has tenants in it, whose insurance quote scares the buyer's lender, or whose name is not yet on the title.
Selling a tenant-occupied two- or three-family takes a cash buyer
Most Bridgeport rental buildings are two- and three-family houses, and a financed owner-occupant generally needs a unit delivered empty at closing. That is why occupied buildings on the East Side and in Mill Hill linger while turnkey singles sell quickly. We buy with tenants and leases staying in place, and our page on selling when you are done being a landlord explains how it works.
Behind on the mortgage? Connecticut sets a law day, not an auction date
Connecticut does not auction a foreclosed house. The court hands the owner a law day, and once it passes unpaid, redemption ends and the lender takes clear title, with junior lienholders getting their own law days in reverse priority order (Connecticut Judicial Branch Law Libraries, 2025). Qualifying owners can apply to the state's Foreclosure Mediation Program. For an East End owner with thin equity, that date decides everything, and our guide to selling a house in foreclosure covers what options remain.
Inherited a Bridgeport house? The small-estate affidavit will not pass it
Connecticut's small-estate affidavit only works under $40,000 in solely owned assets and no real estate, which rules out a house every time (Connecticut Probate Court Administrator, 2026). A Black Rock Victorian or a North End colonial still needs the estate opened in the decedent's own probate district, with a fiduciary named before any deed gets signed. Nothing forces a fast decision, and our inherited property guide walks through the steps.
Coastal water and carrying cost are the two Bridgeport-specific costs
The South End and the waterfront blocks of the East End and Black Rock sit in FEMA flood zones, and Irene in 2011 and Sandy in 2012 both put water into them. Flood insurance and lender underwriting are where those sales stall. Add a 43.45-mill fiscal 2026 rate (Connecticut OPM, FY 2026) and the seller-paid conveyance tax, and an empty house gets expensive to hold. Connecticut also requires most residential sellers to give the buyer a written property condition report or credit them $500 at closing (Connecticut DCP, July 2025).
Are cash home buyers in Bridgeport legit?
Bridgeport has legitimate cash home buyers alongside bad actors, so the label alone tells you nothing. Who buys houses for cash here? Mostly small renovation shops, landlords who own two- and three-family rentals, and national direct buyers such as Propcash. We act as the principal: our own name lands on the contract, and closing runs through a Connecticut attorney and title company.
How to vet a cash buyer in Bridgeport
A legitimate buyer can show proof of funds, puts the offer in writing, and never asks for a fee upfront. Watch anyone pushing you to sign the day they walk through the house, or asking for the deed before closing happens. Our guides to the 10 questions to ask any cash buyer, the red flags to watch for, and what to expect from a cash buyer apply to every buyer working Fairfield County, us included.
What Bridgeport sellers ask us
How is Propcash different from Bridgeport "we buy houses" companies?
Most "we buy houses" outfits hand you one take-it-or-leave-it number and hope nobody measures it. Propcash is a direct cash homebuyer: we price your Bridgeport house against Fairfield County market data, show how we reached the figure, and can close quickly and confidently.
Are cash home buyers in Bridgeport legit, and who buys houses for cash here?
Legitimate cash buyers do work in Bridgeport, but so do plenty of bad actors, which is why the check matters more than the label. Fairfield County's active buyers are mostly small renovation shops, owners of two- and three-family rentals, and national direct buyers like Propcash, which buys as a principal and closes through a Connecticut attorney and title company. Always ask for proof of funds and a written offer before you sign anything.
What happens if I fall behind on my Bridgeport mortgage?
Connecticut handles this through the court system, and strict foreclosure, not a public auction, is the typical result: the judge sets you a law day, and if the balance is not paid off by then you lose the right to redeem and the lender receives clear, unconditional title. Junior lienholders each get a law day too, assigned in reverse order of their priority (Connecticut Judicial Branch Law Libraries, 2025). The time between now and that law day is what actually matters, and since Connecticut runs a Foreclosure Mediation Program for homeowners who qualify, it is worth talking to a lawyer about your case early.
Can I sell an inherited Bridgeport house before probate is finished?
In most cases the estate needs to be opened before a sale can proceed, since Connecticut's small-estate shortcut only applies when the decedent's solely owned assets are $40,000 or less and do not include real estate (Connecticut Probate Court Administrator, 2026). For a Bridgeport decedent, that estate opens in the Bridgeport Probate Court, and it is that appointment that gives a fiduciary the authority to sign a deed. There is no deadline forcing the decision.
Can you buy my East Side two-family or three-family with tenants in place?
Often, yes. We buy occupied two- and three-family houses across Bridgeport without requiring you to end a tenancy first, and the leases simply transfer along with the building. Most financed owner-occupants need at least one empty unit at closing, and that single rule is why tenant-occupied buildings on the East Side and in Mill Hill linger on the market. Selling to a cash buyer sidesteps that problem entirely.
Do you buy Bridgeport houses in coastal flood zones?
Yes. Low-lying blocks in the South End and along the East End and Black Rock waterfront took water in Tropical Storm Irene in 2011 and Superstorm Sandy in 2012, and FEMA flood-zone designations there drive insurance cost and can stall a financed buyer at underwriting. We buy those houses as-is. Confirm your own parcel against the FEMA Flood Map Service Center before relying on any zone.
Do you buy houses with open code violations or building-department issues?
Yes. Open permits, blight citations, and unresolved code violations are common on older Bridgeport houses and are a routine reason a retail sale falls apart. We buy with the violations in place and take them on after closing, so nothing has to be fixed, cleaned, or cleared first.
Do you buy houses with underground oil tanks?
Yes. Buried and abandoned heating-oil tanks are a familiar issue in older Connecticut houses, and the possibility of soil contamination is what makes a lender and its insurer nervous. We buy as-is, without asking you to remove or test a tank first, and we handle decommissioning after closing.
How fast can you close on a Bridgeport house?
A cash sale can close in as few as 7 days, though most Bridgeport closings actually land somewhere between 10 and 14 days. Because Connecticut closings go through an attorney and title company rather than a lender, the appraisal and loan-approval steps that slow down a financed sale simply do not apply. Need more time to pack? You set the date.
How much will Propcash offer for my Bridgeport house?
What we offer comes down to location, condition, and where current values sit. The Bridgeport median sale price ran about $412,227 over the three months ending August 2026, up 5.7% year over year (Redfin, June 2026), and prices vary sharply between the Black Rock waterfront and the value tier east of the harbor. We price against recent Fairfield County sales and show you how we got to our number, with no obligation to accept.
What does Connecticut's conveyance tax cost a Bridgeport seller?
Connecticut charges the seller a state conveyance tax of 0.75% on the portion of the price up to $800,000 for a residential dwelling, 1.25% to $2,500,000, and 2.25% above that (Connecticut DRS, 2026). A municipal conveyance tax of 0.25% applies on top, and municipalities designated as targeted investment communities are authorized to add up to another 0.25%, so confirm your town's current rate (Connecticut DRS). A typical Bridgeport sale sits well under the first state threshold.
Are there any fees or commissions, and do you buy in every Bridgeport neighborhood?
There are no fees on our side: no agent commissions, no closing costs, no inspection fees, no cleanout charges. The only cost is the conveyance tax Connecticut charges the seller. We buy across Bridgeport and Fairfield County, including Black Rock (06605), Brooklawn and the North End (06606), the South End and Downtown (06604), the West Side (06604), the East Side (06608), Mill Hill and the East End (06607, 06610), plus Fairfield, Stratford, Trumbull, and Milford.
Questions? Call (615) 552-4296 or text us. We respond in minutes.
Ready to Get a Fair Cash Offer for Your Bridgeport House?
Share your property details and get a fair cash offer based on Fairfield County market data. Takes 2 minutes, and there is no obligation to accept.